At 12:21 on a Tuesday in April I sat at my desk with a half-eaten lunch pushed aside and two state tax returns open on the screen, both of them claiming the same $1,847 of June dividends as if they were long-lost siblings fighting over one sandwich. The Ohio return had my old address and my old withholding. The North Carolina return had my new address and a confidence I did not share. Both wanted it all. Neither was wrong about the money, and both were gonna be wrong about the year unless somebody did the arithmetic they were each declining to do: $9,400 of dividend income and $6,200 of grasped gains, split across a year I had also split, on May 9, when a moving truck took my household 470 miles from Columbus to Raleigh.
The stakes sat in a number I keep in my head the way some people keep their blood pressure: about $700. That was the realistic cost of doing this wrong — double taxation on the overlapping dividend window, penalty interest on a late amendment, and an Ohio residency claim I had not yet proven I could beat, all stacked on top of each other like the sandwich dispute. My employer had already flagged that my W-2 would arrive with two states' boxes filled, which meant the returns would be read closely, and close readers find what you failed to allocate.
The scariest number in the whole file was not on either return. It was 183 — a figure I half-remembered from a moving forum — versus a statute that actually says 184, and the difference between those two numbers is the story of nine nights I spent on an air mattress in an empty house. All of it is below, cuz counting days turned out to be the entire ballgame.
a moving truck and a tax window
Nobody hands you a card at the U-Haul counter explaining that moving states also moves your tax year, partially, in two directions at once. Ohio would tax what I earned while I lived there, through May 8; North Carolina would tax everything after, and each dividend lands with whichever state the calendar says I lived in when it was paid. My brokerage paid its large annual distribution in June, twenty-six days after the truck, which made it cleanly North Carolina's — but four modest quarterly dividends, including a January one, belonged to Ohio, and the two states' software did not agree on how politely they would share. Part-year residency sounds like a form you fill out. It is actually an argument you hafta win with arithmetic.
the same 1,847 on two returns
The June dividends of $1,847 became the flashpoint, cuz I had sold $6,200 of index fund shares in March — still an Ohioan — to pad the moving budget, and the fund's year-end accounting dumped its capital gains distribution on me in June, by then a North Carolinian. Both returns wanted the full slice taxed at full rates. The March sale had already generated a capital gains tax bill I owed Ohio for, and the June distribution was pure North Carolina money, yet the automated check on each state's form kept flagging the other state's slice as unreported. The fix exists and goes by different names in different states: a credit for income tax paid to another state, claimed on Ohio's Schedule of Credits, supported by North Carolina's official copies of every relevant form. Gettin it required allocating every dollar of that $9,400 of dividends and the gains by residency days — 128 days an Ohioan, 237 a Tar Heel — and defending the allocation if anyone ever asked.
nine nights in an empty house
The truly frightening part was not the allocation. Cuz our Columbus house sat unsold til August 2, Ohio law could deem me a full-year resident if I kept an abode there and spent enough of the year inside its borders — and I spent nine nights there in July alone, sleeping on a borrowed air mattress, finishing the move-out, painting the baseboards a landlord-neutral gray. Each of those nights was a data point in a test I had not grasped I was taking. Had the total crossed the statutory line, Ohio could have claimed my entire year — every dividend, every dollar of the June distribution — and North Carolina would have handed back almost nothing in credit, because two full residency claims do not cancel each other out. They stack.
184, not 183
Here is where the forum nearly cost me. The number 183 circulates everywhere as the residency threshold, and I had planned my year around it the way you plan around a speed limit you heard from a friend. The Ohio statute, read slowly, at a kitchen table, with a highlighter, says 184 contact days — and one night of difference is one night of full-year exposure, which is not a rounding error when the year in question includes $9,400 of investment income. I recounted June twice, then July, then asked my wife to recount the calendar without telling me her total first. Hers matched mine. The gap between what I remembered and what the law said had a width of exactly one air mattress night.
the wall calendar with red ticks
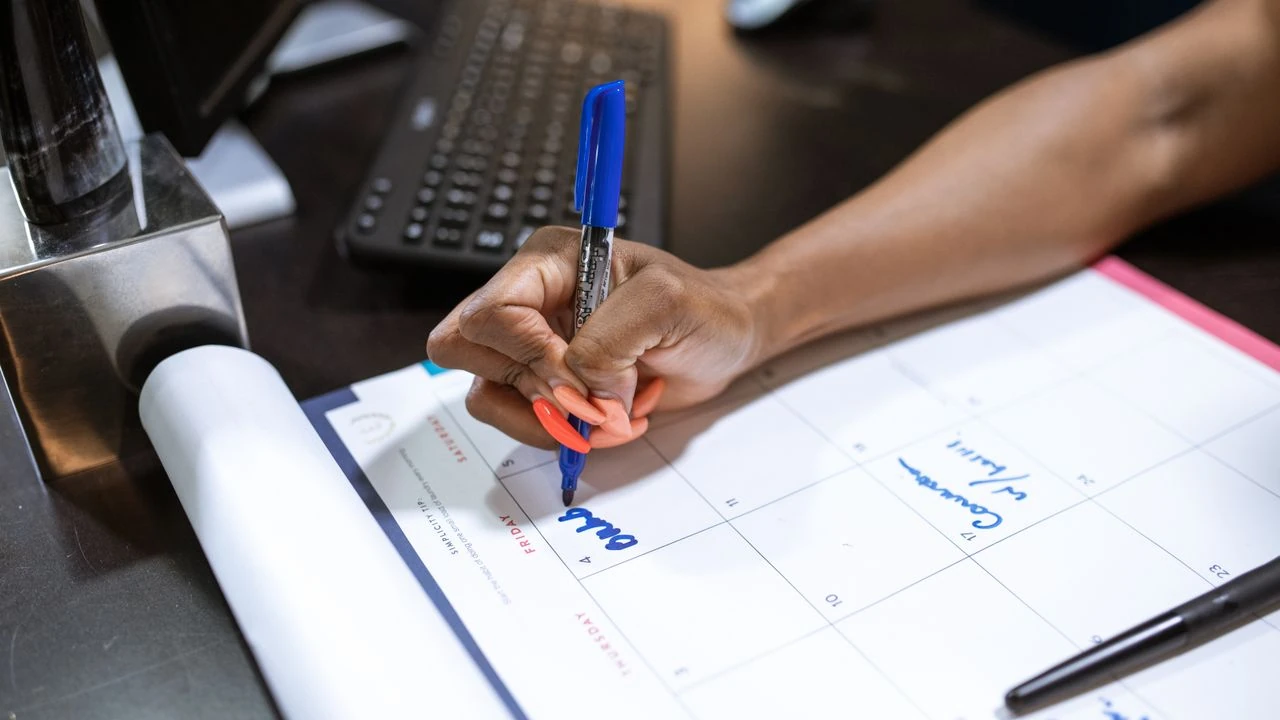
I built the day count the way an auditor would, which is to say joylessly and twice. The wall calendar went up in the new house in May, one red tick for every night physically slept in Ohio, a blue tick for North Carolina, and every travel day — a work conference in Chicago, a wedding in Cincinnati I nearly forgot, two funerals of distant relatives that swallowed a whole week — got its own color and its own documentation, because states do not take your word for where your body was. Total red ticks: 137. Comfortably, verifiably under the line, with a margin narrower than I would have liked and wider than I once feared. I photographed the calendar on December 31 and filed the photos alongside the returns, where they still sit, waiting politely to be believed.
what the allocator said
The allocation math itself ended up almost insultingly simple once the days were fixed. Ohio's taxable window covered January 1 thru May 8; my brokerage's January dividend of $1,103 and the March sale's gains belonged there, with the capital gains tax I had already paid Ohio credited on its own schedule. North Carolina's flat 4.25 percent took everything from May 9 forward, including the $1,847 June distribution, and the credit worksheet confirmed the two states' claims touched but never overlapped. Nobody got paid twice. Final answer: Ohio got $412, North Carolina got $517, and the refunds — $96 from one state, $134 from the other — arrived within nine days of each other in June, like siblings who had ultimately agreed to split the sandwich.
the binder nobody asked for
Somewhere in my home office there is a green folder that no government has ever requested: calendar photos, the tick tally, the allocation worksheet, the credit worksheet, one highlighted printout of the residency statute with the word 184 boxed in pen. Preparing a defense nobody demanded is either anxiety or gardening, and I have stopped needing to know which. What I know is that the folder cost me one Sunday and would have cost a paid preparer several hundred dollars to reconstruct after the fact, and the difference between those two prices is most of what I now know about moving.
one state, one number now
This spring's desk had a different shape: one state, one return, one line for the dividends, filed in a single afternoon with no worksheet and no highlighter in sight. The wall calendar is still up, ticking nothing now, and I keep it partly as a warning about what a casual year can hide — a house that sells too slowly, a distribution that lands one day past a border you moved. The $1,847 that began the argument sits, in retrospect, exactly where it should: North Carolina's column, taxed once at 4.25 percent, by the state where the mail actually finds me. Two states wanted that sandwich. One state got it. The lunch I ate that Tuesday, for the record, went cold anyway.