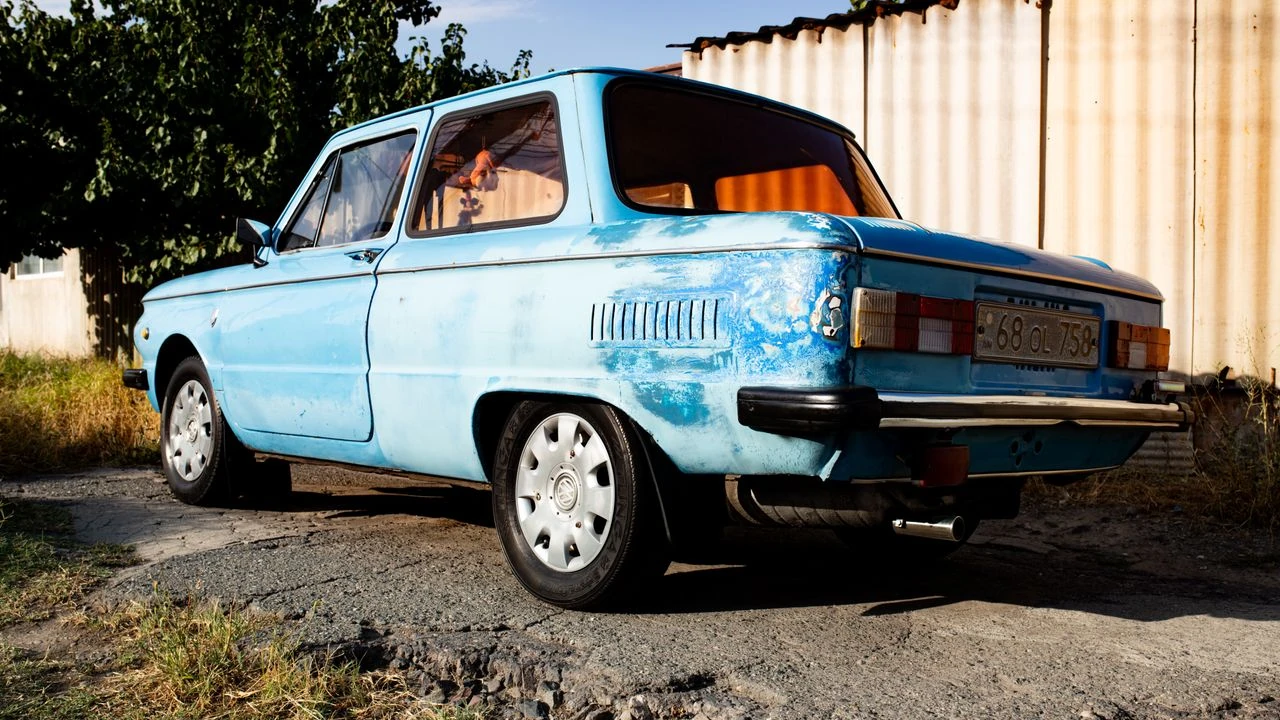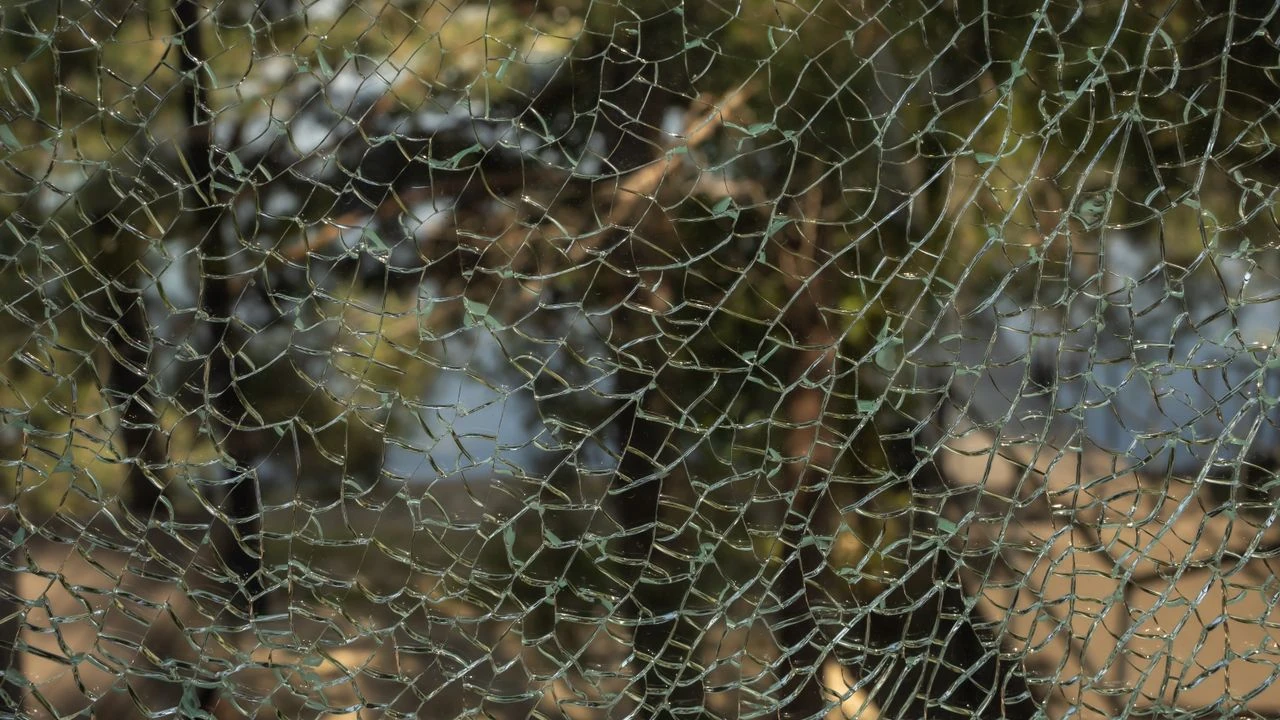
Sunday, April 5, 8:15 in the morning, I stood in my driveway with a coffee cup balanced on the roof of the Outback and one fingertip inside a crack that had grown across the windshield overnight to the length of a business card. Cold glass, warm finger. The crack ticked another inch while I watched. That sound goes through you.
Here is what the crack was holding hostage. The Outback is a 2018 with EyeSight, which means the windshield carries the stereo cameras that run lane keeping and pre-collision braking, so glass stopped being glass and became equipment. Shop one quoted $729 with recalibration. Shop two wanted $815 and a Tuesday appointment. My car-repair bucket held $2,400 in high-yield savings, and my hand was already hovering over the transfer button, because I assumed any insurance claim would make my premium swell like a bad ankle and eat the difference anyways.
What stopped me was a piece of paper I had never once read in eleven years of carrying insurance: the declarations page, folded behind the ID cards, with a sentence way down at line 9 that I'm gonna make you wait for, the same way I had to.
the rock came off Route 9
Saturday evening, 5:40 PM, Route 9 southbound, a gravel truck two cars ahead shed a pebble the size of a pencil eraser and it ticked off my hood like a tossed dime. I remember the little no-harm-done breath. By the time I parked at home, a chip had bloomed into a star. Overnight the star went lateral. Windshield glass holds a grudge.
a windshield that thinks for the car
The EyeSight cameras bolt to the glass itself, so any replacement means the car hasta relearn where the world is, and that is the recalibration line item, $90 to $180 depending on who you ask. Skip it and the lane assist drifts you toward oncoming traffic with total confidence. Nobody says that part out loud in the quotes. Shop one bundled the recalibration properly at $729 all-in. Shop two called recalibration optional, which should be illegal, and might be somewhere.
A windshield used to be a windshield. Now it is a sensor array with wipers, and the price tags prove it: my old 2008 Corolla cost $260 to re-glass in 2015, and the same rock on the same road would run that car's owner about $700 today once recalibration gets added. The crack does not know it landed on technology. Your wallet finds out anyways.
two quotes and a Monday deadline
Monday morning I made the calls from the kitchen table, notes on a yellow pad, because heat cycles grow cracks and the forecast promised 80 degrees by Wednesday. $729. $815. Two shops, one number apart by a wave of the hand, and every dollar of the difference was headed straight out of my savings account if I chose to pay for it myself. I chewed on that all afternoon. The yellow pad filled with arithmetic that pointed at writing a check I did not want to write.
line 9 of the declarations page
While the coffee went cold I dug into the policy folder instead, mostly to confirm the fear before paying it. Declarations page, line 9, under something called Section VII: full glass coverage, $0 deductible, zero surcharge for glass-only claims. I read it four times. Then a fifth, out loud, to a dog who did not care. Four dollars and ten cents a month had been riding on that line since March 2023.
the rider I never remembered buying
I called my insurer to confirm line 9 was real and not a misprint, and a rep named Oswald pieced together the history in about ninety seconds: a bundle promo in 2023 had tacked a glass endorsement onto the policy for $4.10 a month, I had clicked yeah during an online renewal, and it had been riding along quietly ever since. Two years. Ninety-eight dollars of premiums for a $730 windshield. I have never gotten a better return on anything I forgot I owned.
forty minutes with a phone rep
The claim itself took forty minutes on the phone, no app, no portal, just me, a rep, and a claim number I wrote on the yellow pad in block figures. A mobile glass tech came Thursday and replaced the windshield in my office parking lot, and the recalibration ran Friday morning at a partner shop, with a printout proving the cameras had relearned the road. Total out of pocket: $0. Not low. Zero. The tech even vacuumed gravel dust out of the cowl, which is the kind of luxury I did not know the word claim could buy.
the renewal quote in June
Here is the part everybody warns you about, so I made the rep say it plain: glass-only claims under this endorsement carry no surcharge and no accident flag, and a claim like this never touches your credit score, cuz no credit check happens at all. The renewal quote landed May 20 for the June 1 term, and the premium had not moved a cent off $1,142. The $2,400 in high-yield savings never left the account either, still earning 4.25 percent, still bored. I keep the yellow pad in the glovebox now, under the registration. New rule in this house: read line 9 before touching the checkbook. That Sunday I put a fingertip back on the glass where the crack had been. Smooth as a countertop.